
Naina had opened three product pages on her phone before her first meeting with a financial professional. She had compared the return figures, saved a few questions and decided she would ask which option made the most sense.
She expected the wealth conversation to begin with those pages. Instead, the first question was, “What is this money meant to do for your life?”
Naina put the phone face down. “My son’s education,” she said. Then, after a pause, “And perhaps a different kind of work for me.”
Her son would need the money in eleven years. She hoped to change careers in three. There was also her mother’s medical care and a home loan with twelve years left to run. She had arrived thinking about one amount to invest. As she spoke, it began to sound like several different commitments.
The professional opened a notebook. “Which of these dates can move?”
The career change could, Naina thought. Her son’s education could not move very far. Her mother’s needs had no date at all.
That last answer took longer than the others. Naina knew what her mother’s regular care cost. She could not say what an unexpected hospital stay might ask of her.
They wrote down her household spending: about ₹72,000 a month, including the loan instalment and regular support for her mother. Her emergency reserve was ₹3.6 lakh. At that spending level, it covered roughly five months. It was a starting point for discussion, not an answer to every possible expense.
“If you changed careers, would your income stop?”
“Perhaps for a while. Or it might just be lower.”
Naina had thought about the work she wanted to do. She had spent less time thinking about the months between leaving one job and settling into another.
She turned the notebook towards herself and drew a line under the career-change date. Beside it, she wrote, “What would I live on?”
She had arrived thinking about one amount to invest. It began to sound like several different commitments.
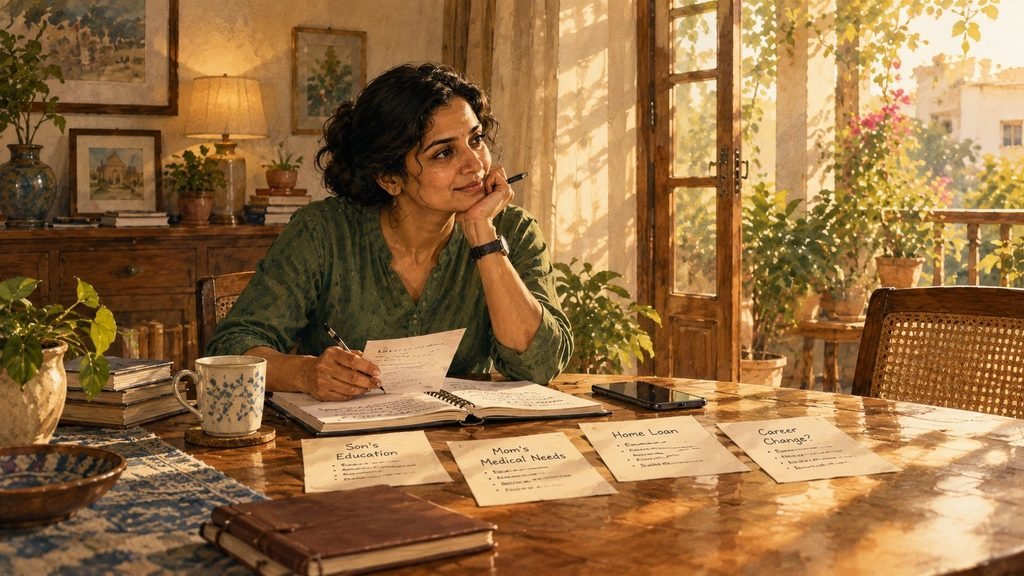
The product pages were still on her phone. None of them could answer that question without knowing more about her circumstances.
For the rest of the meeting, they kept returning to the dates and responsibilities. Money for an unexpected expense needed to be available when called upon. Money for education had a different timetable. The career change needed its own estimate of spending and possible income.
Naina asked whether this meant choosing three different products.
“It means understanding the needs first,” the professional said. “Then we can examine the options, their costs and their risks.”
She left without a recommendation that day. There was more information to gather: the education cost, the spending during a career break and the savings already committed elsewhere.
At home, she reopened the three product pages. This time she did not compare the return figures first. She placed the notebook beside the phone and read the question she had written herself.
