
By the time Rohan opened the thirty-seventh tab, he could no longer remember what he had originally wanted to check.
The first few had been useful. An article explaining interest rates. A comparison of asset classes. A video about market cycles. Then came fund rankings, expert interviews, economic forecasts, portfolio screenshots and a discussion thread in which six confident strangers had offered nine different predictions.
Rohan enjoyed this part.
In his office, he was the person people approached when money came up over lunch. He could explain inflation without searching for the definition. He knew why diversification mattered. He understood that past returns did not guarantee future performance. His financial knowledge was something he quietly took pride in.
Three years earlier, Rohan and his wife, Isha, had started putting aside ₹25,000 every month toward a goal fifteen years away. They had chosen the amount after looking at their income, responsibilities and the time available. The arrangement was not perfect, but it was considered and manageable.
Then Rohan began reading more.
One article made their choices seem too cautious. Another suggested that a different approach had recently performed better. A third warned that the market was unusually expensive. Each new piece of information seemed important enough to require a response.
Over six months, Rohan considered changing their arrangement four times. Twice, he went through with it.
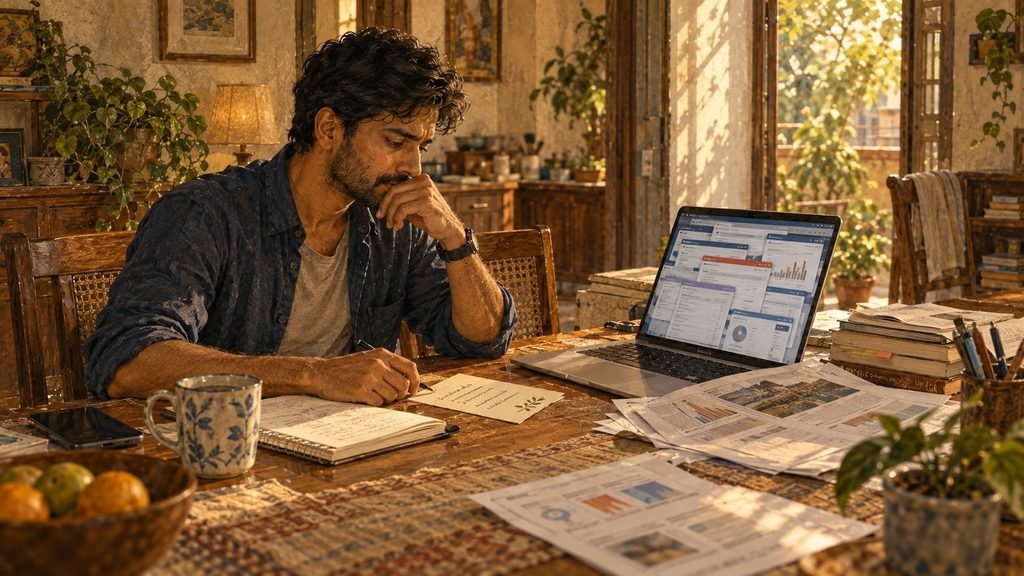
On a Sunday afternoon, Isha found him at the dining table with his laptop open, a notebook beside it and the familiar crease between his eyebrows.
“What are we changing this time?” she asked.
Rohan turned the screen towards her. There were charts, percentages and five coloured lines moving in different directions.
“This could be more efficient,” he said. “And this expert thinks the next few years may be different.”
Isha looked at the screen for a moment.
“Did our goal change?”
“No.”
“The fifteen years?”
“No.”
“The ₹25,000?”
“No.”
“Has anything changed in how much uncertainty we can afford?”
Rohan stopped.
Nothing about their life had changed. Their income was the same. Their responsibilities were the same. The goal and its timeline were the same. He had acquired more information. He had not yet worked out whether any of it changed their plan, or simply made another plan look more attractive.
What had changed was how certain he felt.
Every article had given him another fact, term or argument. Together, they created the feeling that he should now be able to identify the best possible answer. Remaining still began to feel careless. Changing something felt like evidence that he was paying attention.
Rohan closed the tabs one at a time.
Thirty-seven windows disappeared. The last page left on the screen was the note he and Isha had written three years ago. It contained no market forecast. Just the goal, the time available, the monthly amount and the risks they had agreed they could live with.
The note did not know what would happen next.
Neither did the thirty-seven tabs.
But the note knew what the money was for.
Research behind the Story.
- Kaiser, T., Lusardi, A., Menkhoff, L. and Urban, C. Financial Education Affects Financial Knowledge and Downstream Behaviors. Journal of Financial Economics, 2022.
- Arjun, T.P. and Subramanian, R. Defining and Measuring Financial Literacy in the Indian Context. Managerial Finance, 2024.
- Bhatia, B. Indian Millennials’ Financial Literacy and Its Relationship with Financial Instruments and Fintech. Metamorphosis, 2024.
- Asaad, C.T. Financial Literacy and Financial Behavior: Assessing Knowledge and Confidence. Financial Services Review, 2015.
